MPR Reset: CBN Moves To Restore Policy Signal, Boost Lending
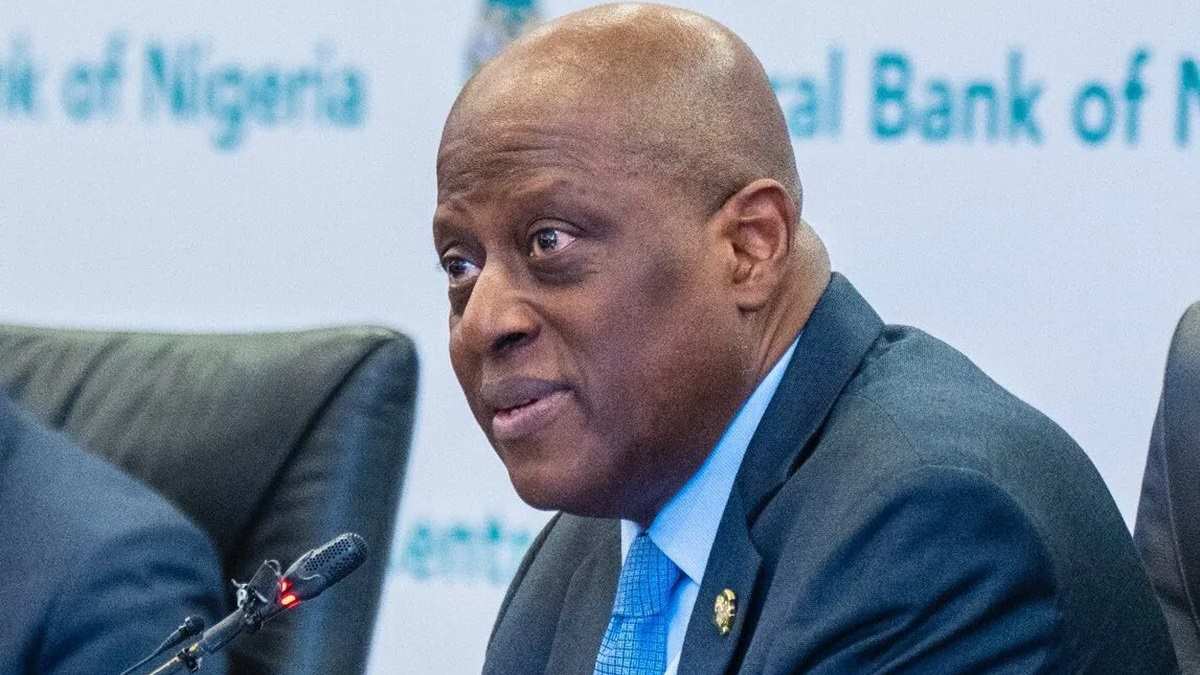
The Monetary Policy Committee (MPC) of the Central Bank of Nigeria (CBN) rose from its 307th meeting in September with a decision that came as a shock to many, cutting the benchmark interest rate by 350 basis points to 23 per cent from 26.5 per cent while resetting the Standing Facilities Corridor to +50/−300 basis points around the Monetary Policy Rate (MPR).
Though a measure many had called for, the steep reduction was unexpected, as many analysts had anticipated only a slight moderation in monetary policy, particularly after the apex bank signalled the beginning of an easing cycle.
But the decision, the CBN said, was not an abandonment of its restrictive monetary policy stance. Rather, it was a recalibration of the monetary policy framework to restore the MPR to its position as the principal signal of monetary policy and bring it closer to prevailing market realities.
Rising from the meeting, the CBN governor, Olayemi Cardoso, explained that the divergence between the MPR and prevailing market rates had weakened the effectiveness of monetary policy transmission.
The reset was therefore an “operational realignment” aimed at strengthening monetary policy transmission, reinforcing the primacy of the MPR, and supporting the transition towards an inflation-targeting framework.
According to Cardoso, the timing of the adjustment was important because the broader macroeconomic environment had become more stable. “The external position is not 5, 10, 15 years; it’s 18 years better than it has been. This is a big deal. The numbers speak for themselves,” he said.
Cardoso pointed to the improvement in the foreign exchange market as one of the factors providing room for the recalibration. He noted that stability in the foreign exchange market was already having broader effects across the economy, particularly in the capital market and investor confidence.
The MPC’s assessment of the economy provided the backdrop for the decision. The committee, which reached the decision unanimously, noted that inflation had moderated for three consecutive months, while external reserves had strengthened and external sector fundamentals had improved.
Headline inflation slowed to 15.39 per cent in August 2026 from 15.43 per cent in July. Food inflation declined to 19.57 per cent from 20.31 per cent, while core inflation fell to 13.29 per cent from 14.97 per cent. The 12-month moving average headline inflation rate also declined to 16.30 per cent in August from 16.89 per cent in July, marking 20 consecutive months of moderation.
At the same time, real GDP growth accelerated to 4.43 per cent in the second quarter of 2026 from 3.89 per cent in the preceding quarter, while the composite Purchasing Managers’ Index rose to 52.7 points in August from 51.1 points in July, indicating continued expansion.
The external position also provided a stronger buffer, as gross external reserves stood at $55.25 billion as of September 18, 2026, the highest level in 18 years and sufficient to finance about 11.3 months of imports.
The Managing Director and Chief Executive of Coleman Technical Industries Limited, George Onafowokan, had described the adjustment as a reset aimed at aligning monetary policy with prevailing market realities.
Noting that the banking sector recapitalisation had increased the equity and lending capacity of banks, with the resulting liquidity helping to push lending rates below the previous MPR, he said while the CBN’s MPR stood at 26.5 per cent, commercial banks were already lending at about 22 to 23 per cent.
“The market found its own level based on the amount of liquidity and the new money in equity in the market. And so it repositioned itself and started lending lower than the CBN was,” he said.
According to him, the latest decision was therefore apt because it acknowledged where the market had already moved to. Onafowokan, however, said the impact of the rate adjustment would not be immediate, but could begin to filter through the economy within the next two to three months.
He also noted that lower interest rates could affect treasury bill yields and influence foreign portfolio investors’ decisions, although Nigeria remained attractive to international investors because of the returns available in the country.
Analysts at Coronation Merchant Bank similarly viewed the decision as an attempt to restore the signalling role of the MPR and strengthen monetary policy transmission. They said three years of aggressive liquidity sterilisation had weakened the MPR’s effectiveness as the primary policy signal.
With the Cash Reserve Requirement at 45 per cent and cumulative Open Market Operations issuance of about N46.56 trillion in 2026, the analysts said the CBN had simultaneously drained system liquidity while offering attractive risk-free returns through the Standing Deposit Facility.
This, they said, encouraged banks to place excess funds with the CBN rather than expand credit, thereby anchoring overnight rates close to the corridor floor and reducing the MPR’s influence on market pricing.
Coronation said the stronger external position provided one of the clearest justifications for the reset, citing a $7.54 billion current account surplus, a $3.51 billion balance of payments surplus, and $54.72 billion in gross external reserves in September.
CardinalStone analysts also said the MPC’s decision reflected the need to align the policy rate with improving domestic macroeconomic conditions while continuing to contain inflation risks. They noted that three consecutive months of disinflation, sustained foreign exchange inflows and the current account surplus had supported the naira and lifted reserves to $54.7 billion, while net reserves moved above $40 billion.
They said the previous 26.5 per cent MPR had become a less effective anchor for interbank and money market rates, with rates increasingly tilting towards the SDF rate as banks increased their participation at the window amid robust system liquidity. The analysts said the reset could therefore help restore the transmission of the MPR to money and interbank markets.
Already, the decision has begun to influence fixed income markets. CardinalStone noted that average Treasury bill yields fell by 43 basis points to about 18.4 per cent, while average bond yields declined by 48 basis points to 16 per cent after the MPC decision.
The broader implication of the recalibration, however, extends beyond financial markets. For businesses, particularly those dependent on bank credit and working capital facilities, lower interest rates could reduce financing costs and make refinancing and new investment more viable.
CardinalStone noted that this could be particularly important for capital-intensive sectors such as power, where high financing costs, delayed receivables and significant infrastructure requirements have constrained investment.
The benefits could also extend to the cement, industrials, and oil palm value chains, as improved economic activity supports investment and working capital requirements. For households, the combination of moderating inflation and lower financing costs could gradually improve purchasing power and demand.
But the CBN’s message remains that the reset is conditional on continued macroeconomic stability. The MPC said domestic output growth was expected to remain resilient for the rest of 2026, supported by improved crude oil production, agriculture and other business activities. It also projected further moderation in inflation, supported by foreign exchange stability, the lagged effects of earlier monetary tightening and improved food supply as the harvest season progresses.
The challenge, therefore, will be for the CBN to ensure that the recalibrated policy framework succeeds in bringing market rates closer to the policy signal without weakening the disinflation gains recorded so far.
For the real economy, the expected test will be whether the reset moves beyond lower yields in financial markets to translate into cheaper, more accessible credit for businesses, stronger investment, and increased economic activity.
The ultimate measure of the reset, however, will be whether the renewed relevance of the MPR eventually strengthens credit transmission and enables the financial system to channel more funds into productive sectors of the economy while preserving progress on inflation and exchange rate stability.
to like, bookmark, and comment.
Comments
Join the conversation:
No comments yet. Be the first to share your thoughts.